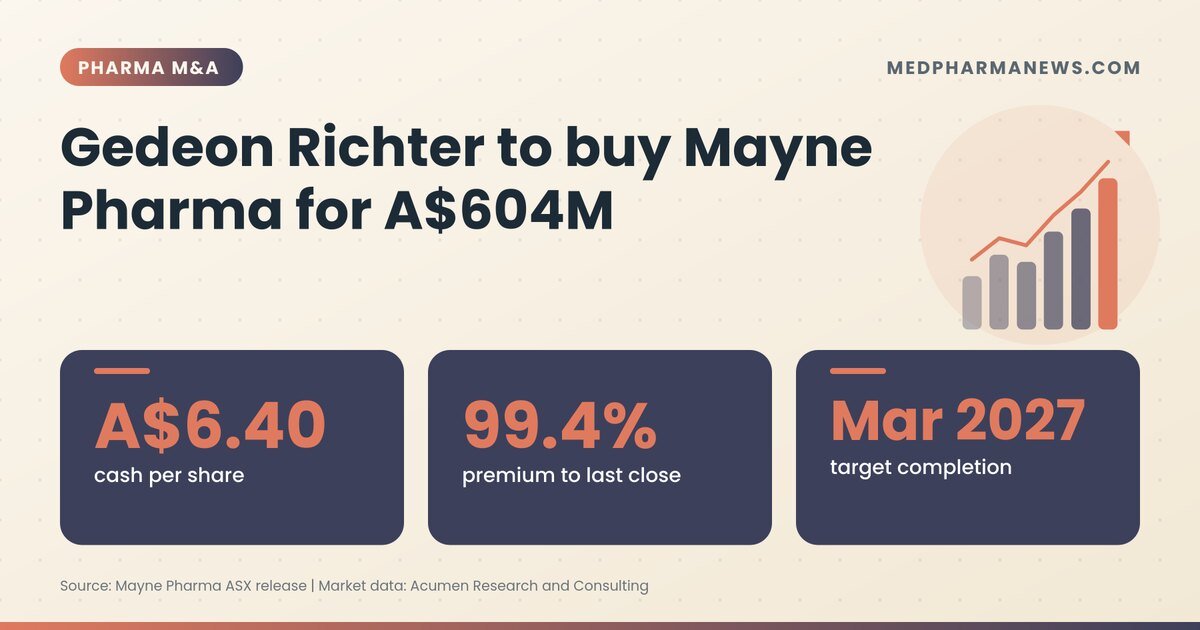
The Gedeon Richter Mayne Pharma deal, announced on 17 November 2026, has Hungary’s Gedeon Richter agreeing to buy ASX-listed Mayne Pharma for A$6.40 a share in cash, valuing its equity at about A$604 million (roughly US$408 million). The offer is a 99.4% premium to Mayne’s previous close, and the shares jumped as much as 86% on the day. What Richter is really buying is a ready-made US women’s health business: a sales force, a branded contraceptive portfolio and a dermatology line, after Mayne sells its non-US operations.
Key takeaways on the Gedeon Richter Mayne Pharma deal
- Price: A$6.40 per share cash via a scheme of arrangement, about A$604 million in equity value on roughly 94.4 million shares.
- Premium: 99.4% to the 16 November close, 124% to the 30-day VWAP and 145% to the 180-day VWAP.
- Mayne’s board unanimously backs the deal, subject to no superior proposal and a favourable independent expert report. Holders of 22.14% say they will vote for it.
- The scheme is conditional on Mayne first selling its International business to Evaris Pharma, plus FIRB, US antitrust, shareholder and court approval.
- Shareholders are expected to vote in late January 2027, with completion targeted for mid-to-late March 2027.
- The bid comes after a 2025 agreement with Cosette Pharmaceuticals at A$7.40 a share fell apart.
Why Richter wants a US foothold
Budapest-based Gedeon Richter operates in around 50 countries and has made women’s health one of its core franchises in Europe. Its biggest US exposure today comes indirectly, through partners such as AbbVie, which sells its antipsychotic cariprazine as Vraylar. Owning a US commercial operation would let Richter launch and sell its own products there rather than relying on licensing.
Mayne fits that need neatly. Its US Women’s Health unit sells an estetrol-based combined oral contraceptive, marketed in America as Nextstellis. Richter already sells the same estetrol plus drospirenone combination in Europe as Drovelis, so the deal joins the two halves of that product’s footprint under one owner. Richter said it views Mayne’s US commercial presence and portfolio as a base for growing its women’s health activities.
Offer terms in numbers
| Term | Figure |
|---|---|
| Cash per share | A$6.40 |
| Equity value | About A$604 million (about US$408 million) |
| Premium to last close (16 Nov) | 99.4% |
| Premium to 30-day / 90-day / 180-day VWAP | 124% / 122% / 145% |
| Break fee | A$6 million, with a reverse fee in set circumstances |
| Shareholders backing the deal | 22.14% (Funicular Funds, Bruce Mathieson, Trium Capital) |
| Funding | Richter internal cash, no financing condition |
| Indicative completion | Mid-to-late March 2027 |
| Cosette’s failed 2025 price | A$7.40 per share |
By our calculation, Richter’s A$6.40 is about 13.5% below the A$7.40 that Cosette agreed to pay in February 2025. With Mayne shares trading near A$5.97 after the announcement, the remaining gap to the offer was about 7%, a spread that reflects the time to completion and the several approvals still needed.
The Cosette backstory
Mayne has been here before. In February 2025 it signed a scheme with privately owned US drugmaker Cosette Pharmaceuticals at A$7.40 a share. Cosette later tried to walk away, and Mayne moved to terminate the agreement after a dispute that left investors with neither the cash nor a clear strategy. The stock spent much of the following period well below the abandoned price. That history explains the size of today’s premium on paper: the shares had been depressed, and the market had largely given up on a takeout.
Mayne chair Bruce Robinson said the board’s priority had been “to maximise value and certainty for all shareholders.” Certainty is the operative word. This time the buyer is a listed, cash-rich strategic acquirer, there is no financing condition, and the largest holders have signed up in advance.
What has to happen before March
- Evaris sale: Mayne must close the sale of its International business to Evaris Pharma, which itself needs approval from Australia’s competition regulator, the ACCC.
- Regulatory clearances: Australia’s Foreign Investment Review Board and US antitrust authorities must clear the Richter purchase.
- Scheme booklet: Expected around mid-December, with the independent expert’s view after a first court hearing.
- Vote and court: Shareholder meeting provisionally in late January 2027, then a second court hearing and implementation in mid-to-late March.
The main risks are a delay at the ACCC on the Evaris sale, or an independent expert finding the price unfair given the earlier A$7.40 offer. A rival bid is possible, but Richter holds matching rights.
Market context: hormonal contraception
The strategic logic rests on contraception being a durable, if modest-growth, market. Acumen Research and Consulting estimates the global hormonal contraceptives market at US$16.8 billion in 2023 and projects it to reach US$25.4 billion by 2032, a compound annual growth rate of 4.8%. Acumen says North America held the leading regional share and that combined hormonal contraceptives, the category that includes estetrol-drospirenone pills, accounted for the largest product share in 2023. For a European company that already sells a newer-generation combined pill, the largest regional market is the obvious one to enter directly.
What it means for the sector
Most pharma M&A this month has been US and European majors buying early-stage science, such as the J&J Ollin acquisition. This deal is the opposite: a mid-sized European company paying for commercial infrastructure in a specialty that bigger drugmakers have largely left. Women’s health has seen several older brands withdrawn or scaled back, as in Pfizer’s Premarin exit in Canada, which leaves room for focused players willing to invest in sales teams.
FAQ
How much is Gedeon Richter paying for Mayne Pharma?
A$6.40 per share in cash, about A$604 million in total equity value, or roughly US$408 million.
When will the Mayne Pharma takeover complete?
The indicative timetable points to a shareholder vote in late January 2027 and implementation in mid-to-late March 2027, subject to approvals and the Evaris sale closing.
Why did the Cosette deal fail?
Cosette Pharmaceuticals sought to withdraw from its 2025 A$7.40-a-share scheme, and Mayne moved to terminate the agreement.
What does Mayne Pharma sell?
After the planned sale of its International arm, Mayne will be a US-focused company built around Women’s Health, including an estetrol-based contraceptive, and Dermatology.
More from Industry Insights.
Sources: Mayne Pharma ASX announcement and scheme terms as reported by Small Caps and Grafa; Reuters market report. Market data: Acumen Research and Consulting. Not investment advice. Last updated 17 November 2026.